The short answer
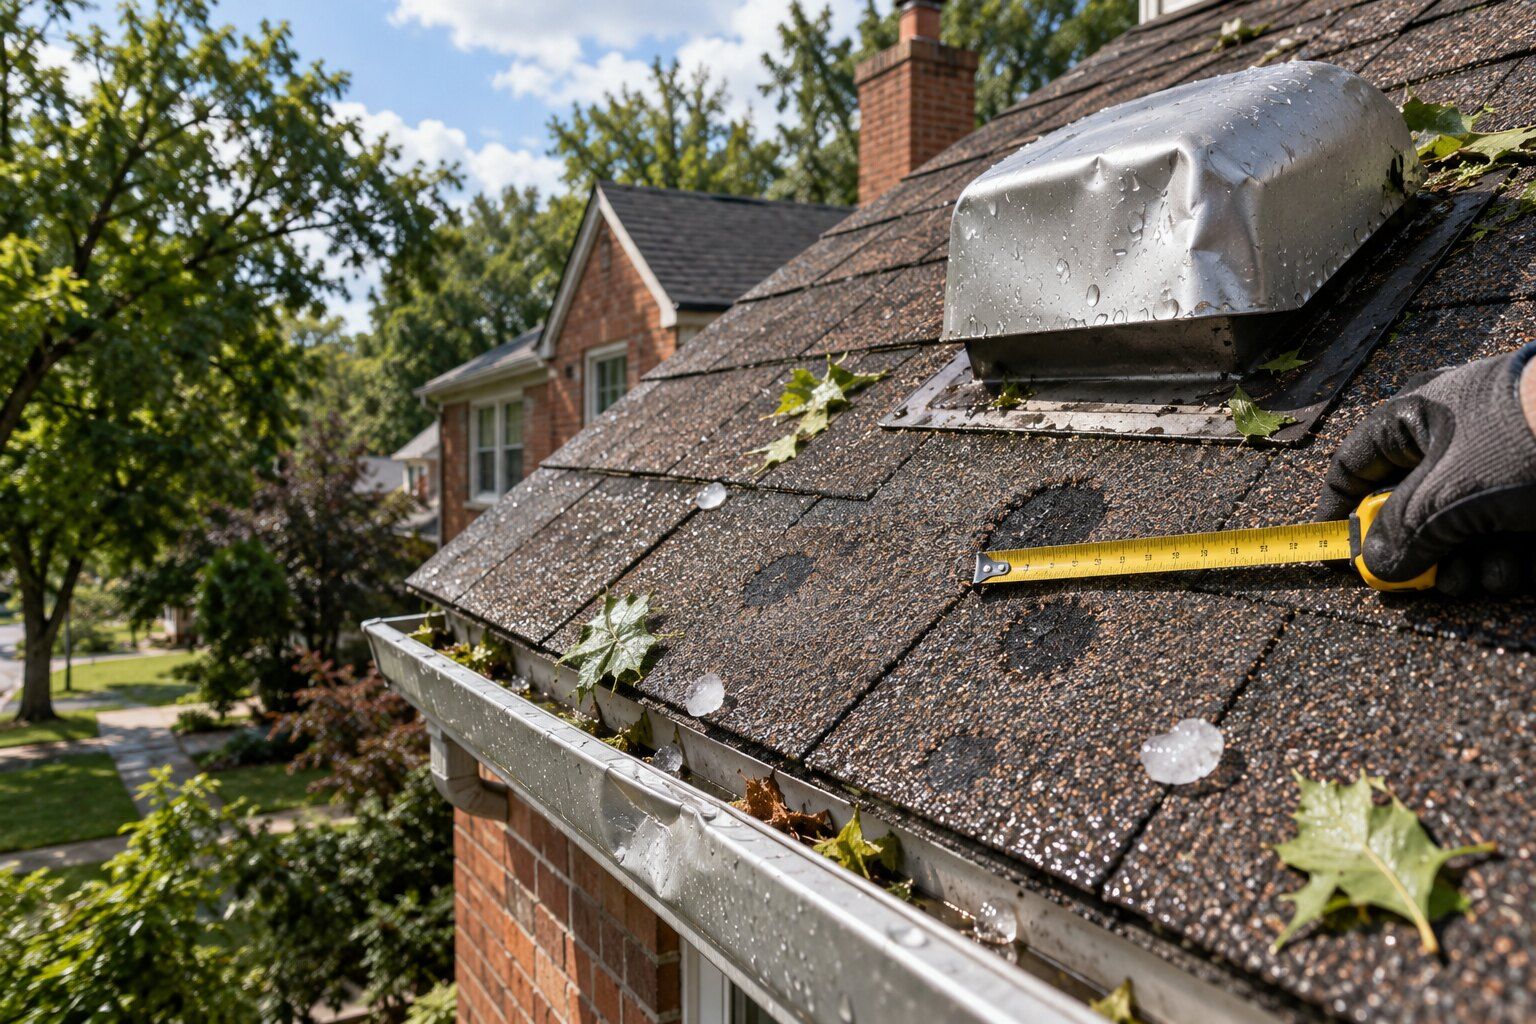
Hail shows up as dark, bruise-like spots where granules are knocked off, dents in shingles, and dings in gutters, downspouts and vents. Standard homeowners policies cover sudden damage from hail and wind, not wear and tear. In Michigan, call your insurer before you hire a contractor, document everything, and know that insurers must pay within 60 days of a satisfactory proof of loss or owe 12% interest. Since July 2025, depreciating labor needs an optional endorsement you agreed to.
Signs of hail damage on a shingle roof
GAF, the shingle manufacturer, lists these signs. Most can be checked from the ground, with binoculars, or in the attic:
- Shingle colors that look like bruising, where hail knocked granules off
- Visible dents or indentations in shingles, and missing, loose or cracked shingles
- Bent or detached flashing
- Dents in gutters and downspouts, and dings in roof vents
- Dents in siding and window sills
GAF also suggests photographing any hailstones still on the ground beside a tape measure, and checking the attic for water before the exterior. Its advice is to leave climbing the roof to the professionals, and the National Roofing Contractors Association says the same: assess the damage from the ground and leave closer inspection and repairs to a roofing contractor.
Need this done?
If the storm damage is spread across an older roof, it may be time for a new one. Say in your request that it's an insurance claim.
Roof replacement in Royal OakWind damage and small hail count too
Wind tends to lift and tear shingles along ridges, rakes and edges, leaving felt or decking exposed. A few missing shingles are often a straightforward repair; see storm damage repair.
Smaller hail matters more than people think. In research reported in October 2025, the Insurance Institute for Business & Home Safety found that repeated hail under an inch caused more cumulative granule loss than a single 2-inch hailstone, and that weathered shingles hit by smaller hail were roughly ten times more susceptible to damage in later severe storms.
Stay off the roof
Don't climb up after a storm. Wet shingles, loose debris and damaged edges make it dangerous. Photos from the ground and from an upstairs window are enough to start a claim.
Does homeowners insurance cover roof replacement?
It depends on the cause and your policy. The Insurance Information Institute (Triple-I) says a standard policy covers damage from perils such as hail and other disasters listed in the policy, but "will not pay for damage caused by a flood, earthquake or routine wear and tear." A worn-out roof isn't a covered loss; a roof damaged by a storm can be.
Your roof's age also affects how a claim is paid. Triple-I says insurers may write older roofs at actual cash value rather than replacement cost value. Michigan's insurance regulator, DIFS, explains that actual cash value means the insurer pays the current cost to repair or replace "minus any loss in value due to use or wear and tear." Check your declarations page for which one you have, and for your deductible.
How a roof insurance claim works in Michigan
1. Protect the house and document the damage
DIFS advises taking steps to prevent further damage if it's safe to do so, keeping receipts for supplies such as tarps, and taking pictures or video of the damage. Don't throw out damaged items until your insurer says you can.
2. Call your insurer before hiring a contractor
DIFS says consumers "should contact their insurance company before hiring a contractor." Report the claim through your insurer's claims line or your agent, with your policy number ready.
3. The adjuster inspects
The insurance company's adjuster works for the insurer. DIFS says adjusters "should never ask homeowners for any payment for their services" that the policy covers.
4. Proof of loss and payment deadlines
Under Michigan Compiled Laws 500.2006, the insurer must tell you in writing, within 30 days of receiving your claim, what it needs as a satisfactory proof of loss. A claim not paid within 60 days of receiving that proof of loss is not paid on a timely basis, and the insurer owes 12% a year interest on it, unless the claim is reasonably in dispute.
5. If you disagree
DIFS encourages you to try to resolve a dispute with the insurer first. If that fails, you can file a complaint with DIFS online or call its hotline at 877-999-6442, Monday to Friday, 8 a.m. to 5 p.m.
Michigan's rule on depreciating labor
Some policies used to reduce actual cash value payments by depreciating the labor needed for the repair, not just the materials. DIFS Bulletin 2024-26-INS ended that as a default: for homeowners policies issued or renewed on or after July 1, 2025, an insurer can only depreciate labor and other nontangible items through an optional, standalone endorsement offered with a matching lower premium.
If your settlement shows depreciated labor, ask the insurer whether your policy carries that endorsement.
Storm chasers and contractor contracts
After a storm, out-of-town crews knock on doors. Michigan's Attorney General and DIFS both warn about it. Before you sign:
- Get everything in writing, with no blanks left on the contract, and don't pay in full up front or in cash
- Check the contractor's Michigan license on LARA's licensee search, and ask for proof of insurance and references
- Be wary of pressure to sign on the spot. The FTC's Cooling-Off Rule gives three days to cancel many sales made at your home
- Ask whether the roofer works on insurance claims at all: not every roofer does
If the claim turns into a full re-roof, the roof replacement cost guide lists what a complete estimate should include, so you can check it against the insurer's scope.
Questions about hail damage and insurance claims
Does homeowners insurance cover hail damage to a roof?
Standard policies cover damage from hail as a listed peril, but not routine wear and tear, according to the Insurance Information Institute. How much you're paid depends on your policy, your deductible and whether the roof is insured at replacement cost or actual cash value.
Should I call a roofer or my insurer first?
Michigan's insurance regulator, DIFS, advises contacting your insurance company before hiring a contractor. You can still have a roofer look at the damage and give you a written assessment to compare with the adjuster's.
How long does an insurer have to pay a claim in Michigan?
Under MCL 500.2006, the insurer must specify what it needs as proof of loss within 30 days of receiving the claim. If it doesn't pay within 60 days of receiving a satisfactory proof of loss, it owes 12% a year interest, unless the claim is reasonably in dispute.
Can my insurer depreciate labor on a roof claim?
For Michigan homeowners policies issued or renewed on or after July 1, 2025, only through an optional standalone endorsement you agreed to for a lower premium (DIFS Bulletin 2024-26-INS).
Can I tell hail damage from normal wear?
Not always from the ground. Bruise-like dark spots, dents in shingles and fresh dings in gutters and vents after a storm point to hail, while even wear across a whole slope points to age. A roofer's inspection and the adjuster's report settle it.
Where this information comes from
The facts and figures on this page come from these published pages, checked on October 12, 2026.
- GAF: roof damage from hail, here's what to do next · Shingle manufacturer's homeowner guidance, August 16, 2020
- NRCA: roof repairs after a storm · National Roofing Contractors Association guidance
- Insurance Journal: IBHS study shows smaller hail may be more damaging to roofs · Trade news report of Insurance Institute for Business & Home Safety research, October 2, 2025
- Triple-I: what is covered by standard homeowners insurance? · Insurance Information Institute consumer guide
- Triple-I: how your roof influences your home insurance · Insurance Information Institute consumer guide
- Michigan DIFS: insurance tips and resources following severe weather · State insurance regulator's press release, March 17, 2026
- Michigan DIFS: insurer requirements protecting consumers from surprise reduced settlements · State insurance regulator's press release explaining actual cash value, July 3, 2024
- Michigan DIFS Bulletin 2024-26-INS: depreciation of nontangible items · State insurance regulator's bulletin, November 8, 2024, for policies issued or renewed from July 1, 2025
- Michigan Compiled Laws 500.2006: timely payment of claims · Michigan Insurance Code: proof of loss, 60-day payment and 12% interest
- Michigan Attorney General: storm alerts · State consumer protection bulletin, March 9, 2026
- FTC: the Cooling-Off Rule · Federal consumer guidance, September 2025
- Michigan LARA: licensee search · State license lookup for Residential Builders and Maintenance & Alteration contractors